Wednesday, May 28, 2014

Budgets - Part 2

https://www.flickr.com/photos/68751915@N05/6757849129By the end of the summer, I should have reached all the short term budget goals I've been working on for the past several months. The question then becomes what are my new goals? If it were up to me, getting a Tesla would be the main goal, but I think I'd have a hard time getting my wife to agree to that. Instead, I have come up with the list of goals below. I have not yet allocated specific amounts to them yet, because I won't have any exact figures to work with until my house has been refinanced and all the dust settles from all the other financial transactions that have been going on this month and last.

Master Bathroom Remodel - We remodeled part of our house two years ago and the next area we want to remodel is our master bathroom. Hopefully, the profits from my apartment investment will provide enough funds to pay for this.

Regular Savings - I need to get back to putting 15% of our income into a savings account for emergencies. We have to have some funds available for unexpected expenses or even impulse purchases. This is non-negotiable.

Appliance Replacement Fund - The death of our refrigerator last December really threw our finances into chaos. An unexpected $3,100 expense right at the holidays was not a pleasant surprise and I'd like to avoid that happening again. I plan to accumulate $3,000 in an emergency fund to be used when other appliances die. Our house is 10 years old and  some of the appliances are starting to show their age. The next one to fail I think will be our washing machine. Even if it doesn't fail, I'm thinking I might start replacing appliances anyway. Ten years is a long time and I'm sure all sorts of improvements in both performance and efficiencies have been made since I last bought the appliances so a 10 year replacement cycle might be prudent. We replaced our dishwasher 1 or 2 years ago and, of course, we just replaced our refrigerator. I think our ovens probably won't need replacing, so that leaves our washer and dryer and our second refrigerator as the remaining big ticket appliances. There is no rush to save this money and I plan to build up this fund over several months to a year.


Tesla - Last on the list, but first in my heart. As my spreadsheet shows, I should be saving at least $134 a week towards this and that's just to save the down payment in three years. It's not even taking into account saving the rest of the money I'll need to invest to cover the auto loan. Clearly, I have a long way to go and as the lowest priority goal, this one frequently gets put off when other needs arise. This is one reason why I have been particularly vigilant about funneling all "non-regular" income, such as bonuses, gifts, or online income towards this goal.

So by the end of the summer, I hope to have a budget in place for all these things. It might be a month late, because I do foresee some additional expenses looming. For example, although our cruise is paid for and it is "all-inclusive", anyone who has ever been on a cruise knows you always get a bill at the end for a bunch of stuff that wasn't included. This is usually a couple hundred dollars. We also have a trip to Las Vegas. While we usually win... Sorry... My wife usually wins. I usually lose.. Anyway, while we usually return with most or all of the money we go with, we will still need to pay for meals during the trip and possibly the room, depending on how we get comped. Plus gas for the drive out there.
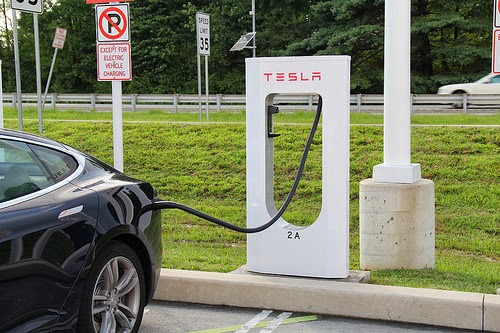

If I had a Tesla, I wouldn't need to pay for gas!


Wednesday, May 21, 2014

Budgets - Part 1

If I was single and living by myself, I would be much more aggressive about saving for a Tesla. However, being married and having a child means my priorities have to change a bit. Although my wife likes the Tesla, she does not burn with white hot desire to own one like I do. So when it comes to budgeting money, compromises must be made.

Where We Were


We're just coming out of a several month period of aggressive savings and debt reduction. Towards the end of last year, we had some pretty big expenses. We took a trip to New York for Thanksgiving. Then Christmas came around, along with all the bills that entails. (For one gift, we replaced my daughter's several year old computer to the tune of several hundred dollars.) Mid-December, our refrigerator died unexpectedly and we spent $3,100 on a new one. Next month, we're taking trips to Las Vegas and a 1 week cruise to Alaska, so we were saving for those during that time as well.

https://www.flickr.com/photos/86530412@N02/7932571974
In my head, I had a rough estimate of a budget and how much we spent on various things, but it wasn't until I signed up at Mint.com that I realized exactly how much we were spending. For example, in March, we spent $407 on eating out at restaurants. That's pretty high and we made an effort to cut back on that. As a result, in April, we only spent $72 eating out. We spent $96 dollars on dry cleaning in February. I made some changes to try to bring that down, such as dropping our laundry off on Tuesdays, when our cleaners offers a 15% discount, instead of Mondays. I also started making a conscious decision to wear shirts that could be washed at home. As a result, in April, our dry cleaning expense dropped to $56.

Between the New York trip, Christmas, and the refrigerator, we had racked up about $5,000 in credit card bills over two different cards, with interest rates of 15.9% and 11.9%. As the saying goes, when you find yourself in a hole, the first step to getting out is to stop digging. So we cut back on pretty much all unnecessary expenditures and diverted all our extra cash to the credit cards. We normally deposit 15% of our paychecks into a savings account. Because the savings account is only paying about 0.5% interest, it made more sense to send that 15% to the credit cards for an instant return of 15.9% or 11.9%.

On top of that, I was also saving $175 a week and putting it towards the cost of our cruise and our Las Vegas trip. After all of our other expenses, such as our mortgage payment, grocery bills, and utilities, were paid, we didn't have much left over.

Where We're Heading

Those several months of austerity paid off. Our credit cards are now paid off. Our cruise has been paid for and we've reached our budgeted goal for the Las Vegas trip. I'm finally seeing the light at the end of the tunnel. I've added on one more goal - I want to have my wife's car paid off. (Mine is already paid off.) We still owe about $4,400 on that and the monthly payment is $383. By redirecting our 15% savings plus the $175 a week that was going towards the other goals towards her car loan, I estimate we'll have that paid off by the end of June.

That will free up another $383 a month. Plus the 15% plus the $175 a week. Additionally, I have a real estate investment that is due to close mid-May - although it's already been pushed back one month - and once that is closed, I plan on refinancing our mortgage. That should free up another $150 or so a month.

Big things are on the horizon. By the end of summer, I should have about $2,500 a month in freed up cash flow. The next step is deciding how to deploy that, which I'll talk about in Part 2.

Friday, May 16, 2014

The Oatmeal Tesla Comic

If you haven't seen this yet, go check it out! This is why I want a Tesla!

http://theoatmeal.com/comics/tesla_model_s


http://theoatmeal.com/comics/tesla_model_s

The love this guy has for the car makes me certain I'm going to have tough time holding out and not buying one the second I accumulate enough for a down payment.

Wednesday, May 14, 2014

Goal Progress: May 2014

At the beginning of each month, I'll post an update on my goals, including a brief discussion of any notable events that might have occurred during the previous month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

As this is the first entry, there's not much to report. The chart below shows my savings since the start of the year. I should note that, to date, all the funds I have saved have come from money outside of my or my wife's regular paychecks. So that means I've only saved money that has come to me from a couple sources: ad revenue from my blogs, income from the online classes I've published, any money received as gifts, and any bonuses I might receive from work. I actually started saving way before January, but I just chose that as the starting point for this chart.

Last update: May 1, 2014
Last value: $4,881
Percent of Goal:  4.28%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.

Events Of Note Last Month: none.