Showing posts with label goal update. Show all posts

Thursday, June 24, 2021

2 Year Post-Finale Follow Up

Last updated: June, 2021
Net Worth: $2,006,775
Change from May, 2020: +$777,524

Now, we have finally come to the end. The absolutely-final, no-more-to-come-after-this last post of this blog.

Another Year Gone

Sadly, COVID is still with us. At least now there is a vaccine. Everyone in my family is fully vaccinated and I am fortunate that no one I know got sick or died from it. It's looking like we are over the hump now and things are starting to open up again. People are planning trips once more, including us. After one and a half years of being away, we are finally returning to Las Vegas for our vacation tradition!

We were very lucky to be minimally impacted by the virus. Neither I nor my wife got laid off or even had our work hours reduced. We both switched to working from home full time and my daughter was able to attend school from home as well. Raises were cancelled at my wife's employer, but the virus was actually a huge boon for my employer. We had a record year in 2020 and we are doing even better this year. As a result, I actually got a significant 5-figure bonus for 2020!

All My Teslas Are Paid Off

My last car payment has been made! All our cars are now paid off! Last year, I thought it would take me 1.25 years to finish paying off the last loan and it took about 2 months less than that, partly due to that huge bonus I received.

Here is an accounting from the bank of the total interest I paid on the loan:


Had I paid off my loan on schedule, I would have paid a total of $5,682 in interest. However, I paid the loan off early, taking only 2.75 years to retire the 6 year loan. As a result, I ended up only paying $3,232.56 in interest. I received a $7,500 electric vehicle tax credit on my 2018 federal income tax for buying the car, so that means not only was my car loan free, I came out ahead by $4,267.44. Not bad.

The Tesla Is Still Amazing

It's now been almost three years of ownership and I still love the car. At the end of 2020, we made a second road trip from Washington to Arizona, just like the one I did at the end of 2018. We took the same basic route and stopped at most of the same charging stations.

Much has changed in the two years since our last trip. First, there are a lot more Teslas on the road these days. Second, I noticed many improvements to the charging network. Some of the locations have been expanded with more chargers and some had the new faster V3 chargers installed. And, of course, there are more charging locations in general.

In fact, I've noticed almost all of the Safeway grocery stores near me have installed one or two free electric vehicle chargers in their parking lots. They are level 2, non-Tesla chargers, which means they are somewhat slow and require an adapter for me to use, but free energy is free energy! I can usually gain about a 5% charge while I do my weekly grocery shopping.

Three Years Old And Going Strong

The car has performed admirably for the three years I've been an owner. I currently have 35,173 miles on the car. That's somewhat low for a 3 year old car, mainly because with COVID, I haven't been driving to work at all. Or driving anywhere, really.

The car was rated by the EPA as using 350 Wh/mi (or 35 kWh/100 miles, as their website lists it). As the below image from the car's odometer shows, I'm actually getting 342 Wh/mi over the life of the car. For this statistic, lower is better, so I'm actually coming out ahead of the official estimate.


Maintenance costs are just about non-existent. Apart from getting it washed, I can't even think of any maintenance I had done. Not routine maintenance, anyway. I have yet to even rotate the tires!

Oops. Turns out, that's not true. I had them rotated once, at 6,250 miles. At the time, that was Tesla's recommended guidance. Since then, the official guidance from Tesla for their dual motor vehicles has changed and they now say that the tires only need to be rotated if the tread difference between the front and rear tires is 2/32 of an inch or more (with the rear having less). That hasn't happened yet. I also still have a fair amount of tread left on the tires, although I can see they are wearing. I will probably need to replace them in another 15,000 miles or so.

Total maintenance costs so far: $68 plus tax.

Which isn't to say I haven't spent money on the car. As the above linked-to post shows, I did scrape my wheel once and had to have that repaired at a cost of $350. My paint was also chipped by a flying rock, so I spent $100 on a Tesla paint repair kit to fix that. Apart from car washes, I can't think of any other maintenance-ish things I've had to pay for.

I'm eagerly awaiting the release of the Full Self-Driving functionality, which I purchased when I bought the car. Autopilot has seen vast improvements during my ownership and, from what I've been reading, FSD should perform even better.

Some Interviews

During the past year, I did a couple of interviews for the ESI Money blog. I was Number11 in their Six Figure Interview series and was Millionaire Interview #237 in the Millionaire Interview series.

Investment Performance

My stock portfolio has recovered from the initial COVID drop and has continued to grow.


That chart perfectly illustrates why it's important to practice buy-and-hold in the stock market and not panic sell. Despite my big loss at the beginning of the COVID pandemic in March 2020, by August 2020, the market had recovered. Not only did it recover, but it continued to rise and I'm now at an all-time high.

But it wasn't just not selling and letting the market recover that helped my portfolio performance. I continued to invest and buy stocks during the downturn. This let me buy at depressed prices and, when the market did recover, it supercharged my growth.


Net Worth


May 2020

June 2021


Our net worth took off over this past year, growing by over $750,000! We have surpassed a net worth of $2 million dollars! Amazing. If I wasn't looking at the numbers myself, I would not believe it.

As the above figures show, the growth was mainly fueled by investment gains, but around $60,000 was due to the property value increase of my house. I also paid down over $85,000 in loans. Some of that was principal repayment on my mortgage, but most of that was my car loan. In May 2020, I owed $72,000 on my Model S. Thirteen months later, I owe nothing.

As I previously mentioned, the huge drop in my stock portfolio from when COVID first hit has more than been made up. And with our final car loan paid off, I'm going to be redirecting that money towards investments and paying down our mortgage, so I expect our net worth to continue to grow, possibly even faster.

I first started tracking my net worth in March, 2016. At that time, it was $621,556.05. Now, five years later, it's more than tripled. Not bad!

So as we come out of COVID isolation and life starts to return to normal, things are looking bright. 

Thanks for reading!

Monday, May 11, 2020

1 Year Post-Finale Follow Up

Last updated: May, 2020
Net Worth: $1,229,251
Change from May, 2019: +$202,172

I did not expect to be writing another blog post, but I felt an update would be in order, given all that has gone on recently.

It is mid-May, almost one year exactly after I wrote what I thought would be my final post. A lot has happened since then. COVID-19 struck, killing and infecting thousands and also decimating the stock market and causing unemployment to skyrocket. My wife and I have been lucky in that neither of us has been laid off, although we suspect some sort of temporary furlough may be in my wife's future. Both of us have been working from home for the past month and a half and my daughter's school has switched to online classes, so she is home full time as well.

This new arrangement has taken some getting used to, to say the least.

This is not pretty - but it's not the end of the world either.

As the above chart shows, our stock accounts have declined in value about $150,000 on paper. This actually represents a rebound from the all-time low of mid-March, which was a decline of close to $300,000. Surprisingly, our net worth has manged to remain above $1,000,000, even with this huge decline.

I'm actually eager to buy more shares of index funds, as I think this downturn is a great buying opportunity. I'm torn between building up a cash reserve in case either I or my wife gets furloughed and investing that cash now to buy while the market is low.

What I Learned From The Coronavirus

I am very grateful I had an emergency fund established. It has provided me with a measure of relief, knowing that we have some funds available should our situation really turn south. However, the stock market crash has made me realize I need to adjust my emergency fund philosophy a bit.

Back in 2 B.C. (before COVID-19), my emergency fund consisted of $2,000 cash and the remainder (about $18,000) invested in low cost index mutual funds and a handful of dividend king stocks. Some people say that investing your emergency funds in the stock market is crazy. However, not investing it in the stock market incurs a huge opportunity cost - you will lose out on all the stock market growth for the (hopefully) rare case when you will need cash someday. The concept of opportunity cost has been written about very nicely over at the Early Retirement Now blog in this post. (Also be sure to read the three other posts he links to at the start of that post.)

So what has happened over the past two months is exactly what many people feared - a stock market crash has really cut into the value of my emergency fund. I'll admit I was worried. The market tanked and my first thought was "Shit! Those goes my emergency fund right when I need it the most!"

But when I stopped to think about it, I realized it wasn't so bad. Yes, if I needed more than $2,000 cash, I would be forced to sell some stock at really low prices. Thankfully, I haven't had to do that so far. But did I actually lose money in my emergency fund with this downturn? Here's a screenshot of my emergency fund stock holdings:


As you can see, my cost basis, the amount of money I paid for these stocks ($18,822.26), is still lower than their current market value ($19,346,74). Even after the huge market losses of the past month, I'm still ahead. Even if I had to sell stocks to raise cash after the market crashed, I still would not have lost money.

However, I'm not completely immune to the emotional ups and downs of huge market swings, so I have decided to adjust my emergency fund strategy a bit. Rather than keeping $2,000 in cash, I'm going to keep an amount of cash equal to two month's mortgage payments, because my mortgage is really the biggest monthly expense that I am worried about covering in an emergency. I'm going to go ahead and accept the opportunity cost of keeping about $5,000 in cash. It's a small price to pay for some peace of mind during the next market crash.

And Speaking of Mortgages...

Right before the coronavirus crisis hit, I had started to refinance my mortgage. Interest rates had dropped a fair amount and my back-of-the-envelope calculations showed I could save a couple hundred dollars a month.

I had a 30 year mortgage at 4.125% and decided to refinance to a 5/5 ARM at 2.75% with no points. It's an adjustable rate mortgage, but the rate stays the same for the first five years. My daughter will be going off to college in 2 or 3 years and there's a high probability we will move shortly thereafter, so I'm OK with just a five-year adjustable rate.

The refi process took longer than normal. Banks are swamped with people wanting to lock in lower rates and then, on top of that, the virus hit, slowing everything down more and causing havoc as people were laid off or furloughed. I was asked about three times during the refinancing process to verify my and my wife's employment status. 😀 Anyway, that all wrapped up a couple days ago and now my monthly mortgage is just over $400 less a month than it was. Part of that savings will be going to paying down my car loan and the rest will be invested in the stock market.

One Tesla Is Paid Off!

This month also featured another milestone! We've paid off my wife's Model 3! We managed to pay it off in just about 1 year - we took delivery in March, 2019 and it was paid off in May, 2020! This was well ahead of the four years I had planned.

Because we paid it off so fast, we actually ended up coming out much further ahead than I had hoped we would. We received a $3,750 federal tax credit (which I collected when I filed our taxes last month). At the time of purchase, I figured we would pay about $3,552 in interest on the loan over four years and we ended up only paying $1,084.37 over the life of the loan, which was one year. That means the purchase price of the car was effectively reduced by $2,665.63 (the $3,750 tax credit minus the $1,084.37 interest charges). To put it another way, we were paid $2,665.63 to take out the car loan!


Now, I am going to concentrate on paying off my Model S by redirecting the money we were sending to my wife's car loan to mine. I estimate we should have our final car loan paid off in about 1.25 years.

Net Worth

May 2019
May 2020


Despite the poor stock market performance of the last two months, our net worth still increased over the year since my last blog post.

The gain came from the usual sources you would expect when you are looking over a full year -  a combination of constantly investing some money each paycheck, paying down our outstanding car loans and mortgage, and property appreciation. Slow and steady wins the race.


Back Into Hiding

That's all for now. I'll likely do one really final update in a year or so when my Model S is paid off. Check back then!

Wednesday, September 5, 2018

Goal Update: End Of August 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of August, 2018
Current value: $51,680
Change from last Month: +$3,271
Percent of Goal:  Undefined


Events Of Note Last Month:

The big news, of course, was I bought a Tesla! Not sure what I'm going to write about here each month now, besides continuing to track my net worth. As I mentioned before, I'll likely start counting down until the loan is completely paid off. Right now, however, I'm in a bit of a holding pattern. I've placed an order for the car, but I don't have it yet, so there's no loan. I'm posting all the details of the Telsa buying experience, so you can follow along at home.

My savings took a big jump this month because I've adjusted my budget to be as if I already had my car payment. Instead of sending those funds to a loan, I'm making payments into my savings account. I'm also including in this figure the $2,500 deposit I made when I placed my order.

My SQL courses on Udemy generated $70.99 of income. My courses on SkillShare earned $37.32. All my Tesla savings are in cash right now, so no changes in value due to the stock market. I'm less than $100 away from hitting $11,000 in lifetime earnings on Udemy for my online courses. I hit $10,000 last November and next month I should reach $11,000.

You wouldn't know if from looking at the data below, but I've sped up my credit card payments this month in preparation for the car loan application. I typically pay off my credit card in full each week, but I schedule the payment to be made 3 weeks in the future. This gives me the maximum time for my money to stay in my checking account earning (a pitiful amount of) interest before paying off the credit card without getting charged any (insanely high) interest.

This has the side effect of making it look like I always carry a balance when I really don't. Outstanding credit card balances are reported to credit bureaus at the end of each statement cycle. Therefore, this month I'm making payments within days instead of weeks so it appears my outstanding credit card balances will be low when Tesla pulls my credit report for the loan application. I'm not worried about being turned down for the loan - my credit score is over 800 and I'm making a down payment of about 33%, so there is no way I'd be considered a credit risk. I just want to make sure I get the best rate possible on the loan.

Net Worth Update

Our net worth hit another all-time high, rising $36,098 to $912,595. Our investments rose by about $21,000 and our house went up by about $5,000. Getting close to the one million dollar milestone!!

I'm not sure we'll get there this year. I've got the car purchase coming up and we're approaching the holiday season, which is always expensive. On the other hand, in September, my wife will hit the income cap for social security withholding, so her paycheck will see a big increase which will last for the rest of the year. My plan is to funnel that extra income into paying down the car loan. So who knows. The same thing will happen to me, but in December.

I can't say getting to a net worth of one million dollars was ever a stated goal of mine. It just sort of happened as I started to take control of and manage my finances more. You can draw your own lesson from that factoid.


July 2018
August 2018


Our credit card balance went up, but that was due to the electrical work I had done for the Tesla wall charger. I've got the cash to pay for that and it will be paid before this post is published.

I hate that red dot next to the credit card entry. That means Mint was unable to connect to an account to update it. In this case, the account is our Gap card, which right now has a $125 balance on it. (Back to school shopping, don't you know.) That will be paid in two weeks.

I know our net worth will drop next month at least a couple thousand. While researching the resale value of my current car, I noticed that Mint was valuing it much higher than the Kelly Blue Book site does. More on that in my second post today!

If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, August 8, 2018

The One In Which I Buy A Tesla


A couple weeks ago, my wife came back from the mall and said "I saw the color of the Tesla we’re going to buy!" This was a small joke between us because she and I could not agree on what color our future car should be. I wanted blue (my last two cars have been blue) and she wanted silver (her last two cars have been silver). I am opposed to silver because it’s a fairly common car color - the beige of the car world, as far as I am concerned. She is opposed to blue for who knows why. So we were at something of an impasse on the color, but I figured it wasn't a pressing issue. There was still plenty of time to figure it out.


Then she told me she was walking by the Tesla store in the mall and saw a car that was a bluish grey that she loved. She actually went into the store to ask the associate what it was called, which is pretty surprising if you know my wife. Turns out, it is called Midnight Silver. The image of the color on Tesla's website doesn't give a good indication of what it actually looks like. It's a metallic paint and looks multicolored in the sunlight. It's still more grey than blue, but there are definite hints that it's not quite what it seems. A Model 3 owner who has this color posted some photos here that show the various hues the paint can take on.

Anyway, while talking about the color, she said "You should just buy one before they stop selling that color."

Hmm. Did I hear that right? Did she just give me approval to spend a crap-load of money? I think so, but was I willing to do that?

It took a week or so of thinking about it, but, as the image above shows, I decided to go ahead a put in an order. We went back to the Tesla store, ostensively so I could check out the color myself, and I pulled the trigger. The car is due to be delivered at the end of September.

How I Talked Myself Into It

If you really want to buy something, it's pretty easy to talk yourself into buying it - just ask any of the millions of people in over their heads in debt. While I'd like to think I didn't just go inventing reasons to justify getting the car now, there is likely some part of that in my decision. That's just human nature. So here's my reasoning. You tell me if you think I am just blowing smoke up my ass.

The Incentives

Telsa recently sold their 200,000th vehicle. This means the federal tax credit of $7,500 will start to be phased out. The full credit is still available for people who take delivery of their cars by the end of the year. Conveniently, that now includes me :-)  However, buying now means I will need to take out a loan for the car. Based on my rough estimates, if I put down about 30% and finance the rest, I'll pay about $6,501 in interest charges on a 6 year loan. So the tax credit more than pays for the loan interest. I also plan to pay the loan off early, leading to even more savings. These numbers will be subject to change once I get all the final paperwork done and the numbers are nailed down, but it's looking good on this front.

Tesla currently has a promotion going on where if you get a referral from a current Tesla owner, you can get free Supercharging for as long as you own the car. This is a feature that was included for early car purchasers, but it was recently scaled back. Now, you only get 400 kWh of charging per year for free. I'm sure this is due to the expected increase of Tesla owners now that the Model 3 is starting to roll out in force. Anyway, I found out about this offer on a Saturday and it was due to expire on the following Tuesday.

This is a pretty big deal for me. I know there are a lot of people abusing the free charging, but I don't plan on being one of them. I would like to be able to drive on long trips and not have to pay for energy, but I'm not going to bother charging for free during my daily commute. I just don't have the patience for that. Rather than stop for 15 minutes on the way home to suck up 75 cents of free energy, I'd rather just head home and plug in. The free charging for road trips was a big reason why I wanted to get a Tesla in the first place and I was sad when I thought I was going to miss out on this feature.

To be fair, the "owner advisor" I spoke with at the Tesla store did tell me that Tesla has extended this offer a couple of times, and may do so again. Truthfully, he said, a lot of people complained about it going away and Tesla was finding it hard to stop offering it. Sure enough, the day after the offer expired, Tesla once again announced that it would be extended, this time through September 16, and this time the offer is also good for buyers of the Model 3 Performance model. (Previously, it was only good for Model S and Model X buyers, as well as Solar buyers, before.)

By the way, if you are interested in buying a Tesla, please use my referral code, shown on the right, or click here :-)

The Taxes

The recent tax bill passed by Congress for 2018 limits the federal income tax deduction for state income taxes to $10,000. Washington is one of the few states that has no state income tax but the federal government allows residents of those states to deduct sales taxes paid instead. Our sales tax is a hefty 10%, but that deduction is also capped at $10,000.

I'm sure this is the first step in removing the state income tax deduction altogether. I fully expect this deduction to be further reduced or be completely eliminated in the coming years. I might as well claim it while it's available. Sales tax on the Telsa will be over $10,000.

The new tax bill did double the amount of the standard deduction. For those like me, who are married and filing jointly, the standard deduction is now $24,000. My mortgage interest payments will be about $20,000 in 2018, so I was planning to just take the standard deduction and not bother itemizing. But with the sales tax paid on a new Tesla, I'll have more than $24,000 in deductions, so I will itemize to get a bigger refund come tax time. When you include the $7,500 tax credit, I should be looking at a nice sized refund next year.

Borrowing Is Cheap

Telsa is offering buyers a loan at a 1.74% interest rate. That's pretty darn cheap. I'm sure that's only for the most qualified buyers, but I'm pretty sure I'll fall into that category. Both my and my wife's credit scores are over 800 and we'll be putting down about 30% for the purchase.

My Planned Investments Are Going Away

The planned main investment for my passive income stream has been the real estate backed mortgages I have been investing in with my partner for over 15 years now. I was earning anywhere from 8% to 12% returns on my money. Recently, my partner has run into some difficulties and it looks like the opportunities have been drying up. I'll still likely invest in real estate, but it will have to be with someone else, whose track record is unknown. That means I will be facing more uncertainty and possibly lower returns in the future. That, in turn, means my target savings goal number would have to go up, probably by a significant amount.

We Can Afford It

Look, to be honest, my wife and I make a very good living. She nearly doubled her salary when we moved to Washington and I got a big bump in mine as well. Depending on which source you read and what year's data you use, we may or may not be One-Percenters, but we most likely are at least Three-Percenters. Don't hate us because we're beautiful.

I've already written about how I love budgets. I've got all kinds of savings accounts as line items in our budget - retirement, emergencies, vacations, car and home maintenance, etc. Our emergency fund recently reached a milestone of 5 months worth of mortgage payments. That was my goal, so I'm okay cutting back on that. If I take the roughly $1,500 a month I was putting towards that, plus the $600 per month I was saving towards the Tesla, we can easily cover the car payment and then some. Additionally, I'll still be putting my online income towards the car. It's just this time it will go towards paying off a loan instead of into an investment account. So bottom line: no net change to our budget, even with a huge car loan, and we'll still be saving money in other accounts.

Yeah, mathematically, it's not optimal. Paying off a 1.74% loan early is like earning a 1.74% return on my money and I know I can do better than that with other investments. But apart from a house, this car is the most expensive thing I have ever purchased and I'm not quite comfortable with such a huge loan hanging over my head. I'd like to get it paid off ASAP.

The Intangibles

This month, I turn 50. It's not that big of a deal for me - just another number - but I do realize that there are now likely more days behind me than in front of me. By no means do I feel like this purchase is a mid-life crisis car. I'm not trying to regain my lost youth or anything. However, it is something I would like to enjoy for several years, at least. Based on my savings rate to date, I figure it would be another 5 years minimum until I would be able to save enough to purchase the car using passive income, as was my original plan. That would put me at 55 years old. I don't want to wait that long.

Also, I have multiple sclerosis. I was diagnosed 18 years ago and, apart from a slight loss of vision in my right eye, I have, thankfully, remained largely unaffected. However, it's an unpredictable disease and it is conceivable that sometime in the future I may not be able to drive. It would suck if I never got my Tesla before that happened.

A friend on Facebook reminded me that there are opportunity costs. What will I miss by holding off on purchasing a Tesla now?  Possibly a lot of enjoyment, that's for sure.

So What Now?

I'm sorry I was not able to buy a Tesla with passive income. I know in my heart that it can be done and that it would be a totally cool thing to do. I just don't have time to amass the capital needed. If I had started 5 or 10 years earlier, I am confident I could have done it. My daughter is young enough that I know she can, should she choose to.

Now that I've abandoned my goal of buying a Tesla with passive income, what will happen with this blog? I plan to keep posting, but the focus may shift slightly. I'm pretty sure I'll be posting a lot about the Tesla experience, everything from the buying process to my adventures driving it, so hopefully, you'll continue to visit.

Rather than a percentage counting up towards a savings goal, I'll probably start counting down until the loan is paid off. (Yes, I'll be paying it off early!) This blog was, really, a means to force me to continue to save towards this goal. Publicly posting my savings was a good motivator to keep saving and not abandon my dream. I'm sure public postings will be just as strong a motivator towards paying off the car loan early.

What are your thoughts about my decision?

Wednesday, August 1, 2018

Goal Update: End Of July 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of July, 2018
Current value: $48,409
Change from last Month: +$2,285
Percent of Goal:  44.52%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:


My SQL courses on Udemy generated $128.15 of income. My courses on SkillShare earned $92.80. Big gains this month came from stock appreciation. It was a relatively quiet month in terms of online income, but summer months typically see a slowdown in student enrollment. I do have one piece of rather big news to share, but I'm going to hold off until next week for that.

Net Worth Update

Our net worth hit another all-time high, rising almost $30,000 to $876,448. This completely surprised me, as I haven't made any changes in my saving plans. In checking the numbers, it seems the biggest increases came from my emergency fund account and general retirement accounts. These are invested solely in a Vanguard index fund and a Schwab S&P 500 index fund.

I think I've reached some sort of critical mass of investments where I'm going to start seeing huge swings in value each month depending on how the market moves. The change in value caused by market fluctuations dwarfs any increases caused by my monthly contributions. (Hopefully, these will be fluctuations to the upside!) In other words, an inflection point. This is something many FIRE bloggers talk about. A good post about it can be found over at The Green Swan.

In a surprise development, the value of our house actually dropped by about $3,500. I think that's the first time it has dropped since we bought it about 8 months ago!


June 2018
July 2018


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Thursday, July 5, 2018

Goal Update: End of June 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of June, 2018
Current value: $46,124
Change from last Month: +$1,559
Percent of Goal:  42.42%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:


My SQL courses on Udemy generated $93.97 of income. My courses on SkillShare earned $46.25. I also received $94.91 from a class action lawsuit settlement.

Our annual summer trip to Las Vegas was fun and, although we did not return home with more than we left with, we did lose less than I planned on, so there's that. We told the casino it was my wife's birthday (which was really just 2 weeks away) and we got an offer to upgrade to a swanky 910 square foot suite for only $75 per night, which we took. (Our original deal was a free room plus  $50 in dining credit and $125 in free casino play.) The suite typically goes for between $500 and $1,100 per night, so that was a screaming deal. The room had 2 bathrooms, a small kitchen, and a nice balcony overlooking the Bellagio fountains. My wife also got a small box of fancy chocolate bars. We also got a free dessert at one of the restaurants we ate at. We went with my wife's sister and her husband, plus her other sister. Someone from each group (including my wife and myself) got at least one $1,000 royal flush win on video poker. Good times!

I crossed the $45,000 threshold this month and unlocked that achievement!


Net Worth Update

Our net worth went up $3,456 this month to $848,911 - another new all-time high! Woo-hoo! Not much else to report on this front.


May 2018
June 2018


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, June 6, 2018

Goal Update: End of May 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of May, 2018
Current value: $44,656
Change from last Month: +$3,425
Percent of Goal:  41.07%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:

Wow! My account value really took off this month. I didn't save any more than normal though. The gains were due to Realty Income stock going up about $2.50 during the month.

My SQL courses on Udemy generated $77.30 of income. My courses on SkillShare earned $63.14. That platform seems to be picking up steam and this month's payment was a new high. I also received $32.47 from a class action lawsuit settlement.

With this increase to over 40% of my goal, I have unlocked a new achievement!


Net Worth Update

Our net worth went up $11,885 this month to $845,455 - a new all-time high! Woo-hoo!

This was really surprising because we made several big purchases this month. We bought a new dining room table and chairs, as well as train tickets for our vacation next year. We had cash saved up for these, but we charged them to get the credit card points, which is why our credit card balance increased so much. Next month, after the bill is paid, you'll see a big drop in the Cash category (but with a corresponding drop in the Credit Cards column). Also, $2,000 of that credit card bill is for a business conference I will be attending that my company will reimburse me for.

Zillow said our home increased in value by $7,000 in May This is on top of the $20,000 it said it increased in April. There's nothing more I can say about the Seattle area housing market. If I wasn't living through it, I wouldn't believe it.

Another big wildcard in the works for June is our annual trip to Las Vegas. Lots of potential there for things to swing in either direction!


April 2018
May 2018


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, May 2, 2018

Goal Update: End Of April 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of April, 2018
Current value: $41,231
Change from last Month: +188
Percent of Goal:  37.92%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:

My SQL courses on Udemy generated $116.84 of income. My courses on SkillShare earned $18.86, which is a drop from the $42.25 from last month. It's still higher than the $10 in February though. I also earned $101.62 from ads on my blogs. (That represents almost a full year of ad revenue. Yeah, I'm not working hard to monetize this blog.) Despite all of that income, plus the $600 I regularly contribute to this fund each month, my increase over last month's total was less than $200. Sometimes the stock market sucks.

And speaking of sucky things, I had an unexpected car repair bill in the amount of $1,850. The sunroof on my Prius would not open. First world problem, I know. Actually, if that was the only issue, I would have left it, but it did open a tiny bit before stopping. When I tried to close it, it may or may not have closed completely but when I turned the car off, I got a warning beep indicating that I had a window open, so I wasn't sure it really did close. Given the frequent rain we get here in Washington, I didn't feel it was worth taking the risk of having a leak ruin the inside of my car, so I took it in to the shop for repairs. It turns out the motor that drives the sun roof had somehow died. To replace it, they had to take pretty much the whole headliner apart. A $600 motor plus a lot of labor charges equals a big bill.

Still, I really can't complain too much. I do have a car repair budget / savings account and it had enough funds to cover this. That's not to say I enjoyed forking out that much. All in all, I have no complaints about the car. It's 8 years old with 140,000 miles. It's been fully paid off for at least 6 years. This was the first major repair I ever had to do to it. Heck, I haven't even had to replace the original brake pads yet.

Net Worth Update

I was shocked to see our net worth went up $15,235 this month, which puts us just $3,000 under our December net worth. We're also less than $4,000 away from what I believe was our all-time high set back in May of 2017.

This was a total surprise to me. It didn't really feel like our investments were gaining ground this month. The only figure I was somewhat monitoring closely was the Tesla account and that went down. It turns out, my feeling was correct:


March 2018
April 2018


As you can see, it wasn't our investments that caused the jump in our net worth - it was our house. Zillow says it increased in value by almost exactly $20,000 in April. I've said the Seattle area is a crazy real estate market and at some point, prices will come down. So right now, this feels like a bit of a hollow victory. 


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, April 4, 2018

Goal Update: End Of March 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of March, 2018
Current value: $41,043
Change from last Month: +$2,957
Percent of Goal:  37.74%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:

My SQL courses on Udemy generated $160.94 of income. My courses on SkillShare are starting to gain traction. I received $42.25 from there, up from about $10 in February. We'll see if that's a one-time aberration or if they are actually attracting more students. Again, I'm doing zero promotion for them.

I saw a big rise in my Tesla account this month, which makes up for the horrible drop in February. Realty Income stock made a comeback, which boosted my total. It's still down about 10% from 6 to 9 months ago, so I might see some more upside.

Net Worth Update

Our net worth shows a $21,060 increase this month, coming almost all the way back from last month's $22,919 decline.Stock market volatility continues to drive the large fluctuations not only in my Tesla account, but also our overall net worth.

Our investments dropped about $8,000 in value, but Zillow says our house increased by $20,000, so that offsets the investments drop.


February 2018
March 2018


Next month, our net worth should start going up more rapidly. In March, we bought a new couch and I diverted some of our monthly savings amount towards paying that off. It's paid for now, so those monthly funds will resume going into our brokerage account.

Taxes

We got hit hard by the tax man this year. Even with $17,000 in tax deductible moving expenses, we still ended up owing just over $2,000. With my wife's new job, which almost doubled her previous salary, and my higher salary with my new job (which I just realized I never wrote about here), we got bumped into the 33% tax bracket. Her big relocation bonus she got when we moved to Washington pushed us deeper into that bracket. We did get about $800 back from our Arizona state taxes, so that helps offset the federal tax somewhat.

My CPA says our higher income also means we are now subject to the Additional Medicare Tax and the Net Investment Income Tax.

I don't mind paying taxes, really. I live in this country and take part in the benefits, protections, and services it offers. I don't expect to get those things for free. But I really dislike being surprised each April with a huge tax bill. I don't understand why the government can't get the monthly tax withholding rates more accurate. I realize everyone's situation is different and we all have different deductions, but surely something can be done.

In an effort to blunt the pain each April, for the past two years, I have increased the additional amount I have withheld from each of my and my wife's paychecks. In 2016, we owed $1,900 in federal taxes come April 15. At the time, I increased our additional withholding from $90 to $250 per month. That works out to an extra $160 per month, or $1,280 per year (because the additional withholding didn't take effect until the fourth month of the year).

In 2017, we still ended up owing $1,000 in federal taxes in April. So in 2017, I increased our withholding again to an extra $400 per month. That's another $1,200 per year (again, $150 for eight months, since it didn't go into effect until April.)

This year, we owe $2,100. Now, I will grant you our income was much higher this year due to the relocation bonus, so there's that. But this year, I'm increasing our additional withholding by another $200 per month, for a total of an extra $600 per month withheld for federal taxes. That's an additional $1,600 per year over 2017.

To sum up: we are now sending an extra $7,200 per year to the government over and above what their regular tax withholding tables call for. My wife and I are basically W-2 wage earners. We don't own our own business or have tons of investment income. In other words, those withholding tax tables should be fairly accurate as to what we owe, yet we still have to significantly overpay to avoid a huge April tax bill. Clearly something is askew with those tables.

Check back next year to see how it turns out this time.


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, March 7, 2018

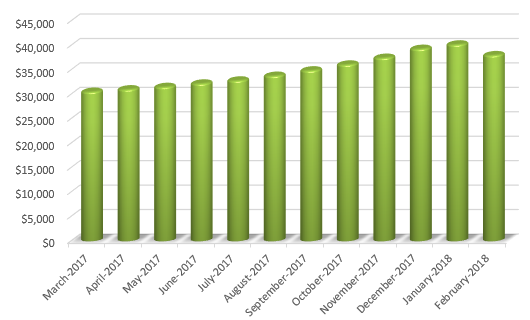
Goal Update: End of February 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of February, 2018
Current value: $38,086
Change from last Month: -$2,186
Percent of Goal:  35.02%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:

Ouch. February hit me pretty hard. The price of my Realty Income stock dropped and handed me a more than $2,000 loss this month - roughly a 5% decline. It wasn't just Realty Income however. The whole stock market had a rough end of February. While the drop in value hurts on an emotional level, I viewed this as a buying opportunity and picked up more shares of O in my Tesla account, as well as purchased some more shares of Vanguard Dividend Appreciation Index (VDAIX), my favorite Vanguard fund, in my IRA account.

My SQL courses on Udemy generated $76.07 of income. Those courses also generated $9.88 on SkillShare.I earned $0.58 in ebook royalties.


Net Worth Update

Our net worth shows a $22,919 decrease this month. That marks two months in a row of a declining net worth. Again, this was mostly due to the stock market tanking.


January 2018
February 2018


If you have any questions or suggestions for topics, please drop me a line in the comments section!

Wednesday, February 7, 2018

Goal Update: End of January 2018

At the end of each month, I post an update of my goals, including a brief discussion of any notable events that might have occurred during the month. The latest month's figures can always be found under the Featured menu in the menu bar at the top of the blog.

Last updated: End of January, 2018
Current value: $40,272
Change from last Month: +893
Percent of Goal:  37.03%


Note that the funds in this account are invested in stock, so there will be fluctuations in value that are outside my control. I never withdraw money from this account, so any dips are purely due to stock price changes.


Events Of Note Last Month:

My SQL courses on Udemy generated $225.27 of income. Those courses also generated $10.25 on SkillShare. Not much else noteworthy happened in January, at least as it relates to my Tesla savings. Just putting some money away each paycheck. I did sell some more puts, but this time they were called, so I ended up buying the stock instead of keeping the cash like the last couple of months. That's fine though, as I like the stock and I'll start collecting a monthly dividend.

Oh, there was one noteworthy event: I unlocked a new achievement!


Net Worth Update

Our net worth shows a $16,688 decrease this month. That's not as bad as it sounds. I try to write the monthly updates on the last day of the month so I get accurate figures, but this time I was late and didn't get around to writing this until February 6th. As you may have noticed, the stock market took a big dive yesterday. Had I checked my net worth on January 31, it would have been $826,175 - just about $6,000 higher. Oh well. I'm in it for the long term and there will be ups and downs in the stock market. I'm not concerned.


December 2017
January 2018


Our credit card debit more than doubled! We're taking a trip to Las Vegas in February and we charged our plane tickets. (Man, flights are a lot more expensive from Seattle than from Phoenix! And, sadly, driving there is no longer an option.) Another part of that big credit card number is a furniture purchase. We've got the cash for both of these expenses, but I charge them to get the credit card rewards before I pay them off.


If you have any questions or suggestions for topics, please drop me a line in the comments section!